EIBOR Explained: How It Can Affect Your UAE Mortgage
Understand EIBOR, how UAE mortgage rates can be linked to it, what EIBOR + margin means, how reset periods work and how changes can affect your monthly mortgage payment.
Miracle Keys Advisory Team
UAE Mortgage Specialists
What exactly is EIBOR?
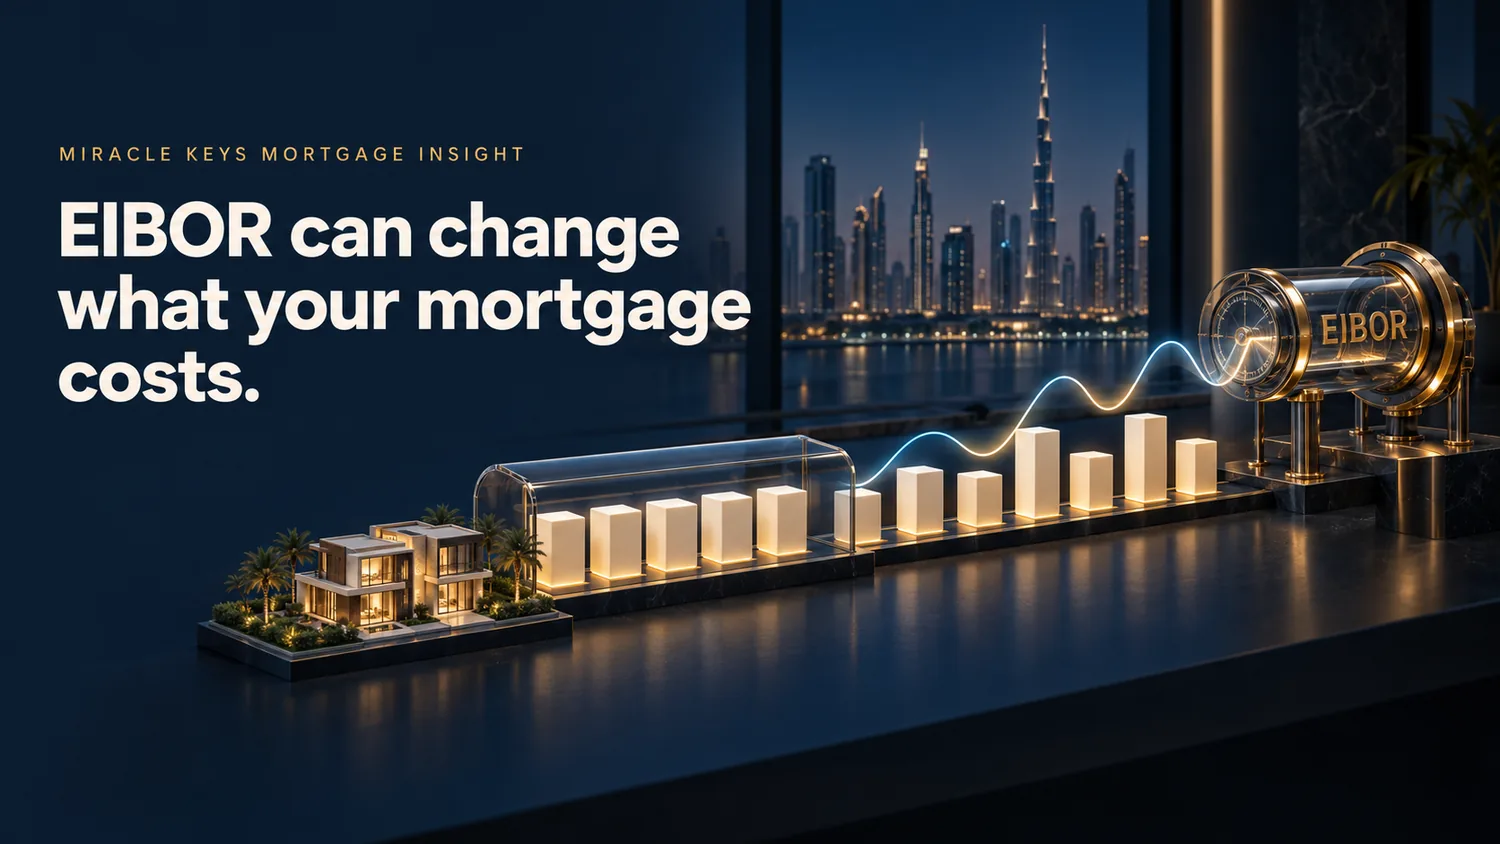
EIBOR — the Emirates Interbank Offered Rate — is a UAE Dirham benchmark used in financial contracts, including many variable-rate mortgages.
For a homeowner, the key distinction is simple: EIBOR is the benchmark, not the final mortgage rate. Your lender normally adds the margin stated in the mortgage agreement.
EIBOR is published for different tenors, including overnight, one week, one month, three months, six months and one year. The Central Bank of the UAE publishes the daily fixings.
Think of EIBOR as the moving part of the formula. The lender's margin is usually the additional percentage written into your mortgage terms.
How EIBOR enters a UAE mortgage rate
In the UAE, a mortgage may be variable from the outset, but a common structure is an introductory fixed rate followed by an EIBOR-linked variable rate. The attractive number advertised at the beginning may therefore apply for only part of a 20- or 25-year mortgage.
Once an EIBOR-linked variable period applies, the pricing may look like this:
Applicable EIBOR + Bank Margin = Mortgage Rate
If the contract says 3-month EIBOR + 1.50%, the bank combines the applicable 3-month EIBOR with the 1.50% margin, subject to the exact terms of the facility.
This is where apparently similar mortgage offers can separate. Two banks may quote almost identical fixed rates today but apply different margins, benchmark tenors or reset terms after the fixed period. Over a long mortgage, those differences can matter more than a small saving in the introductory rate.
A simple EIBOR + margin example
Suppose a mortgage moves from its fixed period to a variable rate of 3-month EIBOR + 1.50%.
Illustrative 3M EIBOR4.00% Bank margin1.50% Illustrative rate5.50%
Using the same simplified formula, if the relevant EIBOR later fell to 3.00%, the rate would be 4.50%. If EIBOR rose to 5.00%, the rate would become 6.50%. The lender's 1.50% margin has not changed; the benchmark has.
This is a simplified illustration, not a mortgage quotation. The actual rate and payment depend on the lender's reset methodology, the relevant EIBOR fixing, outstanding balance, remaining term and any floor, cap or other contractual provision.
What do 1-month, 3-month and 6-month EIBOR mean?
The number refers to the benchmark tenor used in the mortgage pricing formula. Your mortgage documents should identify which one applies.
Benchmark | What it means | What a borrower should notice |
|---|---|---|
1-month EIBOR | One-month benchmark | Can be reviewed more frequently depending on the lender's contractual reset method. |
3-month EIBOR | Three-month benchmark | Commonly seen in UAE mortgage pricing. The bank's review schedule still depends on the facility terms. |
6-month EIBOR | Six-month benchmark | Typically creates a less frequent reference cycle than a shorter tenor, subject to lender methodology. |
One detail is easy to miss: “3-month EIBOR” describes the benchmark tenor. It does not, by itself, tell you exactly when your instalment will change. For that, you need the bank's contractual reset schedule and the EIBOR fixing it applies.
Your EIBOR rate does not necessarily change every day
EIBOR can move between one day and the next. Your mortgage payment normally does not. The lender applies the benchmark according to the review dates and methodology written into your facility terms.
ADCB, for example, currently states that it reviews 3-month EIBOR-linked mortgage rates in January, April, July and October, and 6-month EIBOR-linked rates in January and July, while also noting that review frequency can vary under its terms.
Another lender may use different contractual mechanics. That is why checking the benchmark alone is not enough; you need to understand which fixing your bank uses and when your mortgage is repriced.
What happens when EIBOR rises or falls?
Once your mortgage is in an EIBOR-linked period, the direction is straightforward: if the applicable benchmark rises, the mortgage rate can rise; if it falls, the rate can fall — subject to the contract.
The effect on your instalment is more personal. A borrower with a large outstanding balance and many years remaining can feel a rate movement differently from someone approaching the end of the mortgage.
The variable rate can increase
A higher reference rate can increase the interest rate applied to the mortgage and, depending on the structure, the monthly instalment.
The variable rate may reduce
A lower benchmark can reduce the applied rate, although any contractual floor or other pricing condition still needs to be considered.
The key risk is payment uncertainty. A fixed instalment is easier to budget for. An EIBOR-linked payment can move as the benchmark changes.
Fixed rate or EIBOR-linked: which is better?
Neither structure is automatically better. A fixed period buys payment certainty for a defined time. An EIBOR-linked rate gives you exposure to movements in the benchmark — favourable when it falls, less comfortable when it rises.
The right comparison depends on the fixed-rate duration, post-fixed margin, expected holding period, refinancing plans, fees and how much payment volatility your household budget can comfortably absorb.
Area | Fixed / introductory period | EIBOR-linked variable period |
|---|---|---|
Payment certainty | Higher during the fixed period | Payment can change when the rate resets |
Exposure to benchmark movements | Limited during the fixed period | Directly affected by the applicable benchmark |
What to compare | Fixed rate, duration and exit terms | EIBOR tenor, margin, reset frequency, floor/cap if any |
Long-term view | The initial rate does not tell the whole story | The margin becomes especially important once the mortgage turns variable |
The practical mistake is to compare mortgages only on the first two or three years. If the loan continues for decades, the post-fixed formula can apply for far longer than the promotional period. The margin after the fixed rate therefore deserves a place in the original comparison.
Six EIBOR questions worth asking before you accept a mortgage
Which EIBOR tenor applies?
Confirm whether the mortgage uses 1-month, 3-month, 6-month or another benchmark.
What is the bank's margin?
This is the percentage added to the relevant EIBOR once variable pricing applies.
When is the mortgage rate reviewed?
Understand the actual reset frequency rather than assuming it from the EIBOR tenor.
Is there a minimum rate or floor?
A floor can limit how far the mortgage rate falls even when EIBOR declines.
What happens when the fixed period ends?
Know the exact post-fixed formula before choosing a mortgage on the introductory rate alone.
What would the payment look like at a higher rate?
Stress-test your own budget so you understand the effect of a meaningful increase before it happens.
Do not wait for the first higher instalment to review your mortgage
If your fixed period is approaching its end, do not wait for the new instalment to appear before looking at the numbers.
Start with the existing facility letter: identify the EIBOR tenor, bank margin, reset method, remaining balance and remaining term. That tells you what you are actually moving onto. Only then does it make sense to compare staying with the existing lender against any retention or refinance options available at the time.
Refinancing is not automatically the right answer. Early-settlement charges, valuation, processing, registration and other transaction costs can offset the benefit of a lower headline rate. The comparison should be based on the total financial outcome, not the rate alone.
A mortgage review is most useful before a pricing change, not after it. That gives you time to understand the numbers and decide whether staying, switching or restructuring makes sense.
EIBOR moves — so avoid building an evergreen article around today's number
EIBOR changes over time. As a snapshot, the Central Bank of the UAE published 3-month EIBOR at approximately 3.96% on 4 September 2026. That figure will date quickly — which is exactly why a long-term mortgage decision should not be built around one day's benchmark.
For a live mortgage comparison, check the relevant EIBOR again and apply the actual lender margin and contractual terms. Today's benchmark is context; your mortgage agreement determines how it reaches your payment.
EIBOR and UAE mortgage FAQs
What is EIBOR?
EIBOR is the Emirates Interbank Offered Rate, a UAE Dirham benchmark used as a reference in financial transactions, including some mortgages.
Does EIBOR affect every UAE mortgage?
No. It mainly affects mortgages whose variable pricing is linked to EIBOR. Some mortgages are fixed for an introductory period and become EIBOR-linked afterwards.
What does “3-month EIBOR + 1.50%” mean?
It means the applicable mortgage rate is calculated using the relevant 3-month EIBOR plus a 1.50% lender margin, subject to the facility's contractual terms.
If EIBOR falls, will my mortgage payment always fall?
Not necessarily immediately, and not always by the same amount. The outcome depends on the lender's reset date, the applicable fixing, remaining balance and term, and whether the mortgage contains a floor or other condition.
Can my rate change during a fixed-rate period?
Normally the agreed mortgage rate remains fixed for the stated introductory period, subject to the exact contract. EIBOR becomes relevant once an EIBOR-linked variable stage begins.
Should I refinance when my fixed period ends?
Not automatically. Compare the existing post-fixed rate with alternative options and include all switching costs, fees and the time you expect to keep the mortgage.