Mortgage Pre-Approval vs Final Approval: What’s the Difference?
Understand the difference between UAE mortgage pre-approval and final approval, including valuation, underwriting, property acceptance, lender conditions and mortgage drawdown.
Miracle Keys Advisory Team
UAE Mortgage Specialists
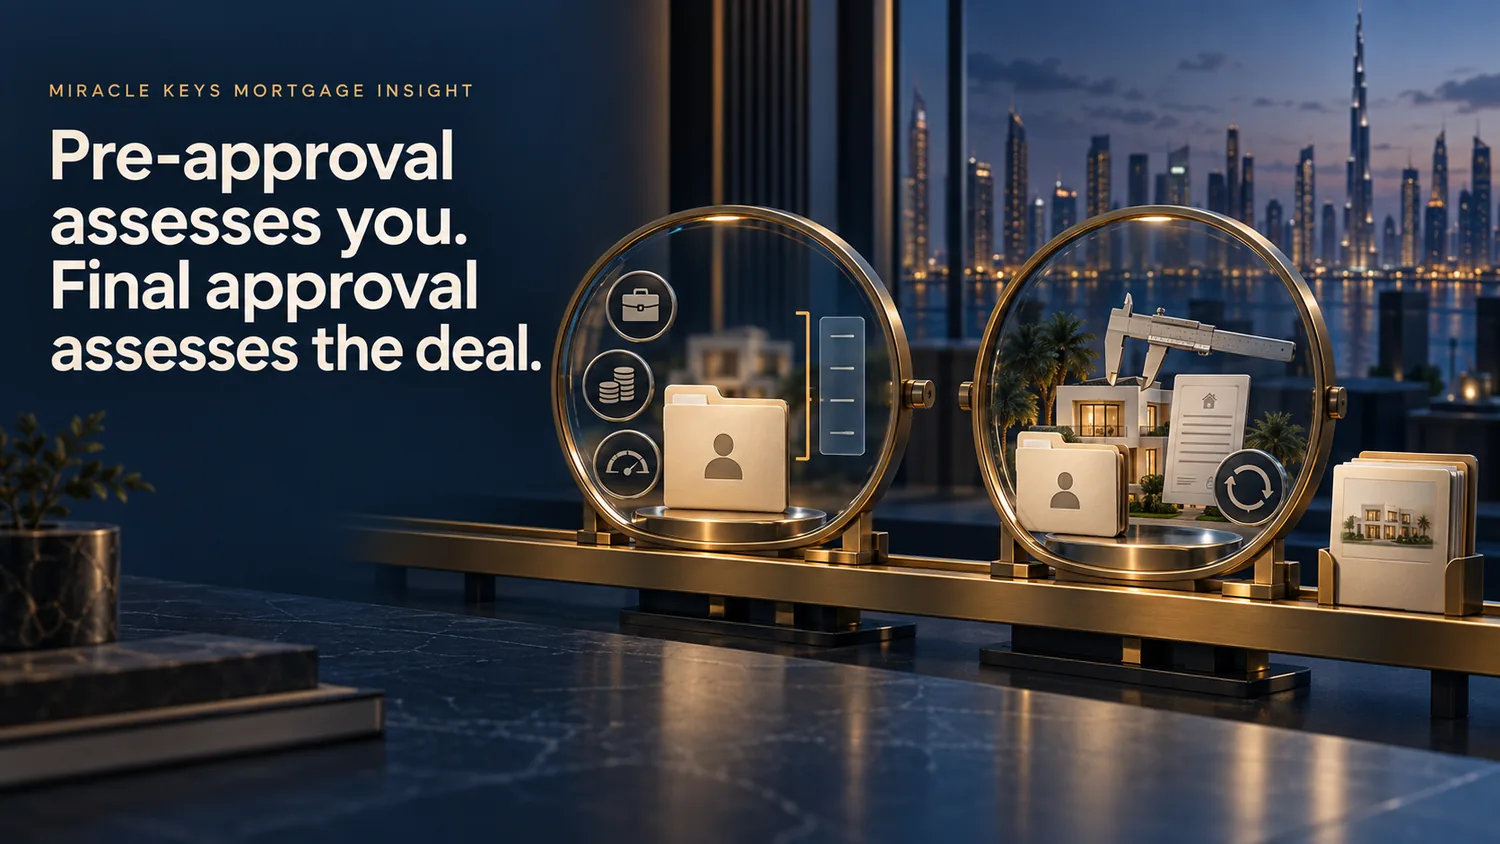
Pre-Approval Assesses the Borrower Before the Full Transaction
Mortgage pre-approval is the lender's early assessment of your borrowing profile before a specific property has usually been fully underwritten. It helps establish whether the bank is prepared to consider you for mortgage finance and on what initial basis.
Income
Salary, qualifying allowances, commission or business income may be reviewed.
Liabilities
Existing loans, credit exposure and DBR are assessed.
Credit profile
AECB and repayment behaviour can influence the decision.
Employment or business
The lender reviews stability, documentation and policy fit.
At pre-approval, the core question is: “Based on what we know today, how much mortgage capacity can this borrower reasonably be considered for?”
What Pre-Approval Actually Gives You
Depending on the lender, the pre-approval may indicate an initial financing amount, assumed term and key conditions. Its real value is not the headline number alone; it is the clearer view it gives you of your financing position before you negotiate seriously on a property.
Pre-approval is a financing position — not a promise that a particular property will be funded.
Final Approval Tests the Borrower and Property Together
Final approval is reached later, when the lender can assess the mortgage as an actual transaction rather than only as a borrower profile. By this stage, the property, valuation, updated financial position and outstanding credit conditions can all affect the decision.
The underwriting question changes from “What can this borrower potentially finance?” to “Can we approve this financing amount against this property, for this borrower, under these transaction terms?”
Pre-Approval vs Final Approval
Pre-Approval | Final Approval |
|---|---|
Mainly borrower-focused | Borrower + property + transaction focused |
Early-stage credit assessment | Advanced underwriting decision |
Usually before property commitment | Usually after property selection |
Based mainly on financial documents | Based on financial + property documentation |
Indicative mortgage amount | Final approved financing structure |
Property valuation may not yet exist | Valuation normally forms part of the assessment |
Conditions remain outstanding | Most credit conditions should be resolved |
Not drawdown | Still precedes completion / drawdown |
Why Pre-Approval Should Come Before a Serious Property Commitment
Risky sequence
Find property → negotiate → sign → pay deposit → then discover how much the bank will lend.
Better sequence
Assess eligibility → compare lenders → get pre-approval → set budget → search and negotiate.
What Documents Are Usually Reviewed at Pre-Approval?
Salaried applicants
Passport, Emirates ID, visa where applicable, salary certificate, bank statements, payslips where required and liability details.
Self-employed applicants
Trade licence, ownership documents, company bank statements, personal bank statements, financials and business information.
Pre-Approval Does Not Mean the Property Is Approved
No. Pre-approval can establish that the borrower fits the lender's initial criteria without establishing that a particular property does. Once selected, the property still has to satisfy valuation, title, project, developer, marketability and other applicable collateral requirements.
Borrower approval and property acceptance are two different parts of the mortgage decision.
Valuation Can Change the Mortgage Even After Pre-Approval
Illustrative item | Amount |
|---|---|
Pre-approved amount | AED 1,600,000 |
Purchase price | AED 2,000,000 |
Bank valuation | AED 1,850,000 |
Potential consequence | Lower mortgage / higher buyer cash contribution |
Purchase price ≠ guaranteed bank valuation.
Why the Final Approved Amount Can Be Lower
Yes. The pre-approved amount is based on the information and assumptions available at that stage. A lower valuation, additional liabilities, updated AECB information, income or employment changes, a different term or final underwriting conditions can reduce the amount ultimately approved.
Why Pre-Approval Can Still End in a Final Decline
Potentially, yes. Pre-approval does not prevent a later decline if the underlying facts change, the selected property falls outside lender criteria or a condition required for final approval cannot be satisfied.
Borrower changes
Employment changes, new debt, income reduction or adverse credit activity.
Property issues
Low valuation, title concerns, project restrictions or lender collateral limits.
A Job Change Can Reopen the Borrower Assessment
Changing employer can materially alter the profile on which the pre-approval was issued. The lender may need to reassess salary, employer eligibility, probation, length of service, employment terms and the available salary-credit history.
If the financial or employment position changes after pre-approval, the approval should be reassessed against the new facts — not relied upon as though nothing changed.
New Debt Can Change the Affordability Decision
New car finance, a personal loan or increased credit exposure can change affordability and DBR. The important point is simple: avoid treating unused borrowing capacity after pre-approval as though it has no effect on the mortgage application.
Pre-Approval and Rate Confirmation Are Not the Same Thing
Not necessarily. Separate approval of the borrower from confirmation of the product pricing. Check whether the quoted rate is indicative or formally secured, how long any pricing is valid and whether completion timing or product conditions can change it.
Pre-Approval Has a Shelf Life
Pre-approval has a lender-defined validity period. If the property search extends beyond it, the bank may require updated documents, refreshed credit checks or a new assessment. The expiry date therefore matters when planning the property search.
Final Approval Uses the Borrower's Current Position
Position | At pre-approval | Three months later |
|---|---|---|
Salary | AED 30,000 | AED 30,000 |
Liabilities | AED 4,000 | AED 7,500 |
Change | Original affordability | New car finance has altered the profile |
Where Form F Sits in the Mortgage Journey
For a typical mortgage-backed purchase in Dubai's secondary market, establishing the financing position before entering a binding property commitment materially reduces avoidable uncertainty.
Pre-Approval → Property Selection → Form F → Valuation → Final Approval → Mortgage Documentation → Transfer
Should Form F Include a Mortgage Clause?
This is a contractual and legal question rather than simply a mortgage question. Before signing, a mortgage buyer should understand how the agreement deals with financing delays or failure and should not assume that using a mortgage automatically creates a consequence-free right to withdraw.
What Happens Between Pre-Approval and Final Approval?
Pre-Approval
The bank assesses borrower eligibility.
Property Selection
The buyer identifies the property.
Sale Agreement
The transaction terms are agreed.
Property Valuation
The lender assesses the property for mortgage purposes.
Final Underwriting
The borrower and property are assessed together.
Final Approval
The mortgage structure is approved.
Mortgage Documentation
The borrower signs the bank's final documents.
Transfer & Drawdown
Completion requirements are satisfied and financing is released under the lender's process.
Final Approval Is Not Drawdown
Final approval is a major milestone, but it is not the release of funds. Mortgage documentation, insurance where applicable, registration, payment arrangements, seller-bank settlement and other completion requirements may still have to be satisfied before drawdown.
Pre-Approval → Final Approval → Documentation → Completion → Drawdown
Approval Labels Vary — the Conditions Matter More
Banks do not all use identical terminology. You may see terms such as approval in principle, conditional approval, pre-approval, final approval, offer letter, facility letter or mortgage offer. The label alone does not tell you how far the application has progressed.
Read what has actually been approved, what remains conditional and what must happen before funds can be released.
Read Pre-Approval as a Conditional Credit Position
A pre-approval can remain subject to satisfactory valuation, property acceptance, updated credit information, employment verification, refreshed documents and final underwriting. Treat those conditions as part of the approval — not as small print to consider later.
Read the Pre-Approval Beyond the Headline Amount
Item | What to confirm |
|---|---|
Approved amount | Is this the amount you expected? |
Validity | When does the approval expire? |
Term | What mortgage tenor is assumed? |
Income | Which income has the bank recognised? |
Liabilities | Are existing commitments correctly reflected? |
Conditions | What still needs to happen? |
Property | Are there restrictions on property type or value? |
Rate | Is pricing indicative or confirmed? |
At Final Approval, Review the Mortgage You Are Actually Taking
At final approval, move beyond the word “approved”. Confirm the financing amount, accepted valuation, LTV, term, expected payment, rate structure, fixed period, post-fixed pricing, fees, insurance where applicable, early-settlement provisions, remaining conditions, validity and drawdown requirements.
Can You Change Banks After Pre-Approval?
Potentially, yes. A different lender may offer a better overall fit on pricing, income treatment, structure or property acceptance. The later the switch occurs, however, the more carefully the new approval and valuation timeline needs to be measured against the transaction deadline.
The Highest Pre-Approval Is Not Automatically the Best Mortgage
Bank A
Pre-approval: AED 1.8 million
Bank B
Pre-approval: AED 1.65 million
The larger pre-approval is not automatically the better mortgage. Borrow only what fits the purchase and your finances, then compare the rate structure, fees, future pricing, flexibility, property acceptance and long-term cost.
The Mortgage Approval Journey, Step by Step
Eligibility Assessment
Which lenders fit your financial profile?
Pre-Approval
How much may the lender be willing to finance based on your current profile?
Property Selection
Does the chosen property fit your budget and lender criteria?
Valuation
What value does the bank accept for mortgage purposes?
Final Underwriting
Do borrower + property + transaction still satisfy policy?
Final Approval
What mortgage is actually approved?
Mortgage Documentation
What terms and conditions are you signing?
Transfer & Drawdown
Are all completion requirements satisfied?
Where Buyers Create Avoidable Risk Between Approval Stages
Mistake | Why it matters |
|---|---|
Treating pre-approval as guaranteed finance | Property and final conditions remain |
Committing to the maximum pre-approved amount | Valuation may create a cash shortfall |
Changing jobs without informing the bank | The borrower profile has changed |
Taking new debt after pre-approval | DBR may change |
Ignoring expiry date | Approval may need reassessment |
Assuming the rate is locked | Pricing may still be conditional |
Signing Form F without considering financing | Contractual risk begins |
Not reading approval conditions | Important restrictions may be missed |
Assuming final approval equals drawdown | Completion conditions still remain |
Choosing the bank offering the highest amount | Structure and long-term cost matter too |
Pre-Approval vs Final Approval FAQs
Is mortgage pre-approval guaranteed?
No. It is normally conditional on the information provided and subject to remaining lender requirements.
Does pre-approval mean my property is approved?
No. Property valuation and property-acceptance checks usually take place after a property is selected.
Can the mortgage amount change after pre-approval?
Yes. Property valuation, updated affordability, documentation or changes to your financial profile can result in a different final amount.
Can a bank decline after giving pre-approval?
Potentially, yes, particularly if material information changes or the property does not satisfy lender criteria.
How long is UAE mortgage pre-approval valid?
Validity varies by lender. Always check the expiry date on the actual approval document.
Can I change jobs after pre-approval?
You can, but the lender may need to reassess the case. A job change should be disclosed.
Can I take another loan after pre-approval?
Doing so can change your liabilities and DBR and may affect final mortgage approval.
Is final approval the same as mortgage drawdown?
No. Mortgage documentation, registration, payment arrangements and other completion conditions may still need to be satisfied.
Can I switch banks after receiving pre-approval?
Potentially, yes. But changing lenders later in the transaction can affect timing.
Should I sign Form F before getting pre-approval?
For a mortgage-backed purchase, obtaining pre-approval first generally gives you a much clearer financing position before making a contractual commitment.