Mortgage Buyout Costs: Is Switching Banks Actually Worth It?
Understand UAE mortgage buyout costs, including early settlement, valuation, processing, mortgage registration and break-even before switching banks.
Miracle Keys Advisory Team
UAE Mortgage Specialists
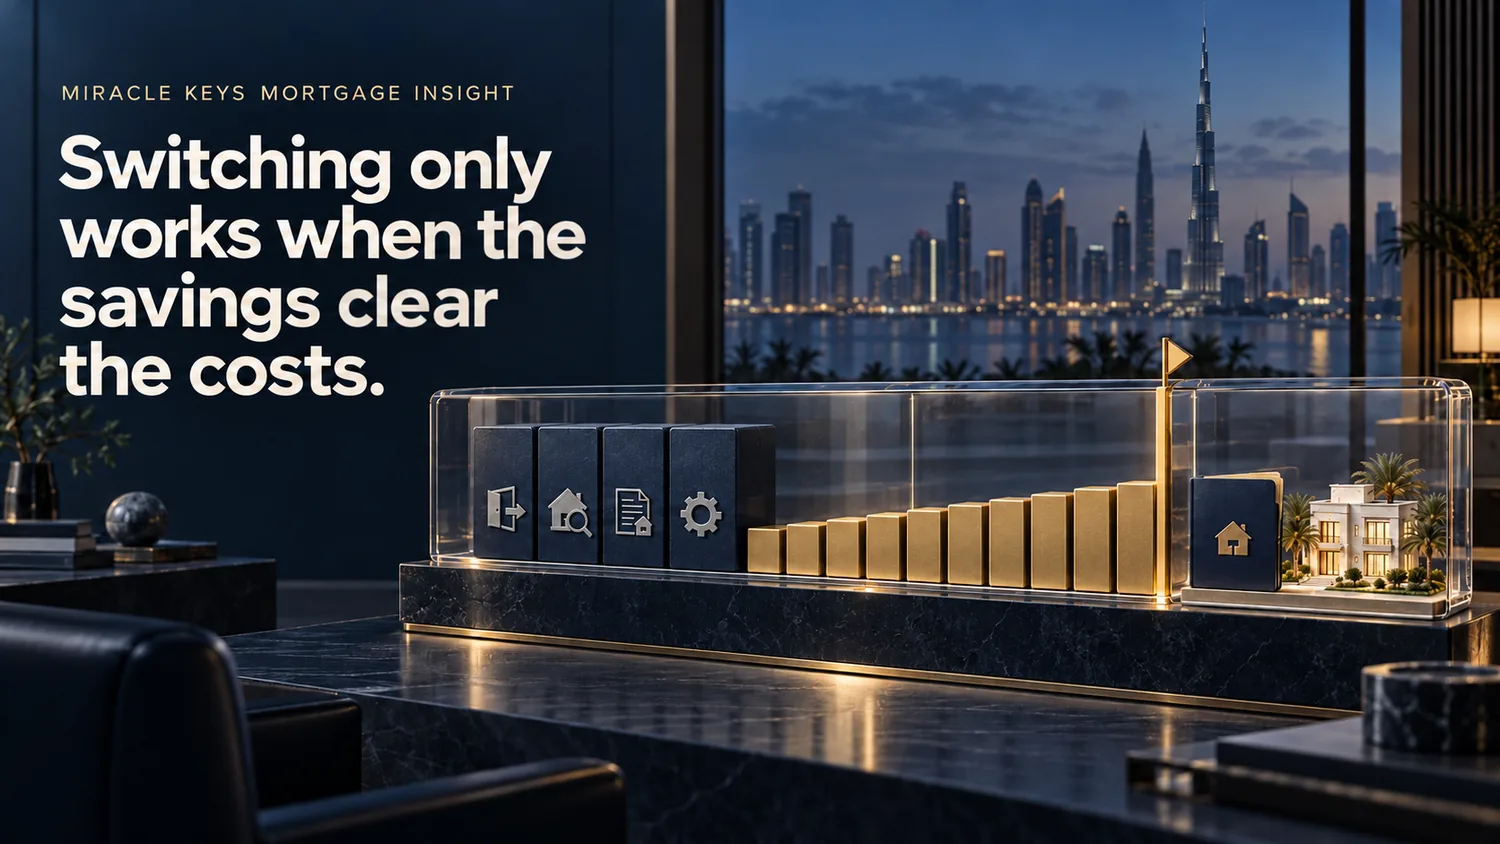
The real question is not whether the new rate is lower — it is whether the switch leaves you better off
Start with today's outstanding balance, not the headline rate. Then calculate what it costs to move that debt, what the replacement mortgage genuinely saves and how long you need to keep it before those savings become a net benefit.
A buyout can improve pricing, payment certainty or the overall structure of the mortgage. But the improvement only counts after the costs of leaving one lender and establishing the next have been included.
A lower rate is a reason to investigate a buyout. It is not proof that the buyout is worth doing.
Think of a buyout as two transactions: closing one mortgage and establishing another
That is why focusing only on the new bank's rate can be misleading. The existing lender has an exit side to complete, while the replacement lender has a new facility to approve, value and register. The relevant costs from both sides belong in the same calculation.
Existing-bank settlement
The applicable early settlement amount forms part of the exit cost.
New-bank processing
The replacement lender may charge processing under its current mortgage proposition.
Property valuation
The new lender normally needs to satisfy its own collateral and valuation requirements.
Mortgage registration / transfer
For Dubai property, DLD mortgage-transfer charges can be a material part of the budget.
Documentation
Liability, release and other transaction documents may carry applicable administrative charges.
Confirmed concessions
Deduct genuine lender-paid costs or rebates only when they are confirmed in the offer.
The first number to obtain is the existing bank's settlement figure
The current CBUAE retail fee schedule caps home-loan/financing early settlement fees at 1% of the outstanding balance or AED 10,000, whichever is less.
On AED 1.5 million outstanding, 1% is AED 15,000. Under that schedule, the cap makes the early settlement fee AED 10,000.
AED 1,500,000 × 1% = AED 15,000 → maximum scheduled fee: AED 10,000
The regulatory cap is useful for planning, but the transaction should be built from the existing lender's actual settlement statement. That tells you what must genuinely be paid to close the facility.
Changing the lender also changes the registered mortgage
Dubai Land Department currently lists the mortgage-transfer fee at 0.25% of the mortgage value. Its current mortgage-transfer service also lists AED 250 for title-deed issuance for an ordinary mortgage, AED 10 knowledge and AED 10 innovation charges for each applicable drawing, and an AED 4,000 service-partner fee plus VAT.
Because the percentage charge follows the mortgage value, larger facilities carry a larger registration component. On a AED 1.5 million mortgage, 0.25% equals AED 3,750.
AED 1,500,000 × 0.25% = AED 3,750
This is the current Dubai mortgage-transfer schedule. Confirm the registration route and charges applicable to the actual property and transaction.
Put every switching cost on one page before comparing monthly payments
Assume AED 1.5 million outstanding. The example below is deliberately a cost map rather than a lender quotation: its purpose is to show what should be included before anyone calls the new mortgage “cheaper”.
Cost | Illustrative treatment |
|---|---|
Existing-bank early settlement | AED 10,000 using the current regulatory cap in this example |
DLD 0.25% mortgage-transfer component | AED 3,750 |
DLD service-partner fee | AED 4,000 + VAT under current service schedule |
Applicable DLD small charges | Additional |
New-bank processing | Offer-specific |
New valuation | Offer-specific |
Confirmed rebates / waivers | Deduct from gross switching cost |
The useful total is the net switching cost after applicable charges and genuinely confirmed concessions. That is the amount the replacement mortgage needs to earn back.
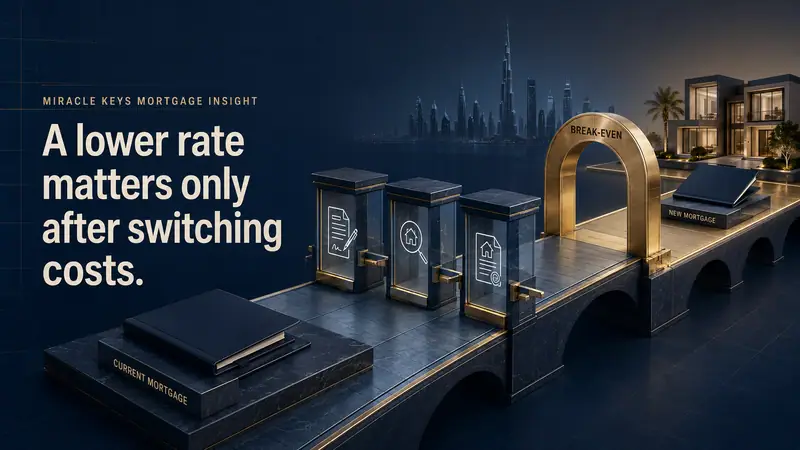
Break-even is the point where the buyout stops recovering its costs and starts creating value
Suppose the final net cost of switching is AED 24,000 and a like-for-like comparison shows a genuine AED 1,600 monthly saving.
AED 24,000 ÷ AED 1,600 = 15 months to break even
During those first 15 months, the monthly benefit is effectively paying back the cost of moving. Only after that point does the switch begin to create a net saving, assuming the pricing and comparison remain valid.
Do not ask only “How much will I save each month?” Ask “How many months until those savings have paid for the switch?”
A strong fixed rate can make the first years look better than the mortgage really is
Read beyond the introductory period. The post-fixed formula, applicable benchmark, lender margin and any relevant floor or reset mechanics can materially change the economics once the initial rate ends.
Keep the repayment term comparable too. Moving from 14 years remaining to a fresh 20- or 25-year illustration can make the monthly instalment look dramatically lower even when part of the reduction simply comes from repaying the debt for longer.
Compare rate with rate, term with term and cost with cost. Otherwise part of the “saving” may be an optical one.
Before paying to leave your bank, find out what it will cost to stay
If the existing lender offers a suitable repricing, put it beside the external buyout before making the decision. Keeping the mortgage where it is may avoid part of the registration, valuation, settlement and administrative cost of a full bank-to-bank switch.
That means the existing lender does not necessarily need to match the competing rate exactly. A slightly higher rate with materially lower switching costs can still produce the stronger net result over the period you expect to keep the mortgage.
Do not ask only “Which bank is cheaper?” Ask “When does switching put me ahead?”
A mortgage buyout begins as a cost. It becomes a saving only when the financial benefit of the replacement facility has recovered that cost.
So bring the whole decision back to four numbers: the outstanding balance, the net switching cost, the genuine recurring saving and the break-even period. Then compare that break-even point with how long you realistically expect to keep the mortgage.
The best buyout is not the mortgage with the most attractive headline rate. It is the switch that leaves you financially better off after the full transaction has been counted.
UAE mortgage buyout cost FAQs
What is a mortgage buyout?
It generally means moving an existing mortgage or home-finance facility to another lender. The replacement lender settles the existing facility and establishes a new one, subject to its approval and completion requirements.
How much is the UAE home-loan early settlement fee?
The current CBUAE retail fee schedule caps home-loan/financing early settlement fees at 1% of the outstanding balance or AED 10,000, whichever is less.
What does DLD charge for a mortgage transfer in Dubai?
DLD currently lists 0.25% of the mortgage value, with additional title-deed, knowledge, innovation and service-partner charges where applicable.
How much lower should the new rate be?
There is no reliable universal rate gap. The answer depends on balance, term, switching costs, future pricing and how long you will retain the mortgage. Break-even is more useful than a fixed percentage rule.
Does a lower monthly instalment prove the buyout is cheaper?
No. The payment can fall because the term has been extended. Compare equivalent terms as well as monthly cash flow.