Debt Burden Ratio (DBR) Explained: How It Affects Your UAE Mortgage
Learn how Debt Burden Ratio (DBR) affects UAE mortgage eligibility, what counts toward DBR, how banks stress-test affordability, and how liabilities influence borrowing capacity.
Miracle Keys Advisory Team
UAE Mortgage Specialists
DBR Measures How Much of Your Income Is Already Committed
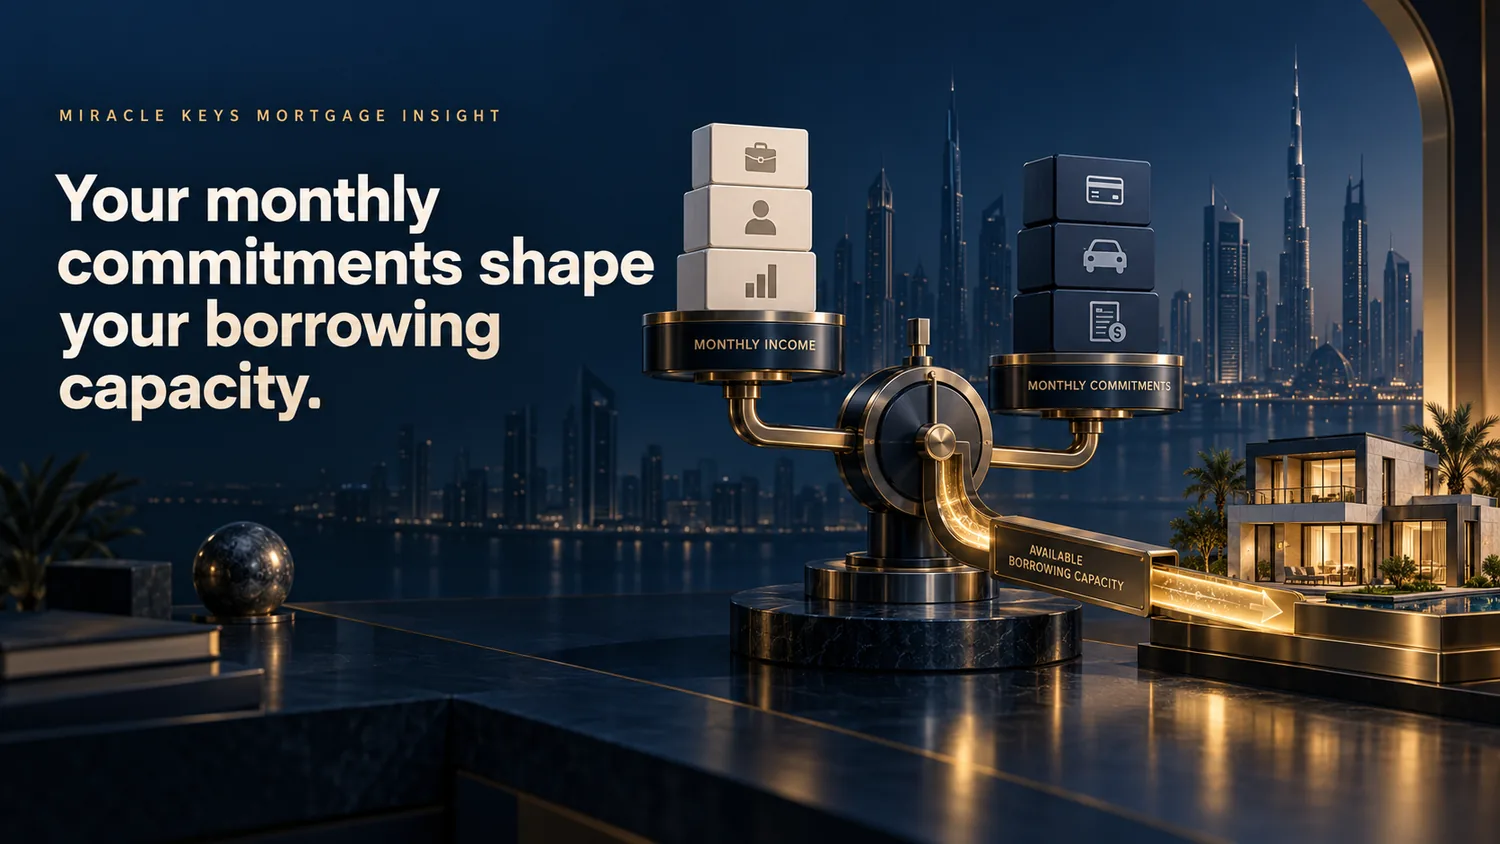
Debt Burden Ratio measures the proportion of qualifying monthly income used to service recognised debt commitments. In mortgage underwriting, it helps answer a practical question: after accounting for the debts you already carry, how much repayment capacity remains for the proposed mortgage?
DBR = Total Monthly Debt Commitments ÷ Qualifying Gross Monthly Income × 100 A lower existing DBR generally leaves more potential room for the proposed mortgage, subject to the lender's remaining affordability tests.
Financial position | Amount |
|---|---|
Gross qualifying monthly income | AED 30,000 |
Existing monthly debt commitments | AED 6,000 |
Current DBR | 20% |
The 50% DBR Limit Is a Ceiling — Not a Borrowing Target
Under the general UAE mortgage framework, DBR is capped at 50% of gross salary and other qualifying regular income. The important word is maximum: it defines an upper boundary for the repayment burden, not an amount every lender must make available to every borrower.
Illustrative calculation | Amount |
|---|---|
Monthly qualifying income | AED 30,000 |
50% DBR ceiling | AED 15,000 |
Existing debt commitments | AED 6,000 |
Theoretical remaining debt-service capacity | AED 9,000 |
The remaining room under the DBR ceiling is not automatically the mortgage payment a bank will approve. Stress testing, income recognition, term, age, credit profile and lender policy can reduce the usable capacity.
DBR Starts With the Commitments the Lender Recognises
Personal loans
Monthly personal-loan instalments reduce the capacity available for a mortgage.
Car finance
Vehicle finance is another recognised monthly debt commitment.
Existing mortgages
Current property finance can materially affect overall affordability.
Credit facilities
Credit-card and other facilities can affect the lender's total repayment assessment.
DBR is not simply salary minus household spending. Mortgage underwriting starts with income the lender recognises and commitments it is required or chooses to include, then applies its affordability and credit methodology.
Credit Cards Can Consume Affordability Even Without a Current Balance
A credit card with a zero current balance should not automatically be treated as invisible to mortgage underwriting. The lender can still consider the facility as part of the borrower's wider credit exposure, and the way that exposure is converted into an affordability commitment can vary by lender.
High limits or multiple facilities can therefore deserve review before an application. But closing, reducing or restructuring credit should be done for a clear underwriting or financial reason — not simply because a generic mortgage checklist says fewer cards are better.
Same Income Does Not Mean the Same Mortgage Capacity
Applicant A
Income: AED 30,000
Existing commitments: AED 2,000
Theoretical room under 50%: AED 13,000
Applicant B
Income: AED 30,000
Existing commitments: AED 9,000
Theoretical room under 50%: AED 6,000
Two borrowers can earn the same salary and have very different mortgage capacity because DBR measures what is already competing for that income.
New Debt Can Reduce Mortgage Capacity Before You Apply
Position | Before new loan | After new loan |
|---|---|---|
Monthly income | AED 25,000 | AED 25,000 |
Existing commitments | AED 2,000 | AED 6,000 |
50% ceiling | AED 12,500 | AED 12,500 |
Remaining theoretical capacity | AED 10,500 | AED 6,500 |
In this simplified example, adding a AED 4,000 monthly personal-loan instalment removes the same AED 4,000 from the theoretical monthly room available under the DBR ceiling. The eventual impact on mortgage amount will still depend on the lender's rate, stress test, term and other affordability assumptions.
The Bank Tests Affordability Beyond Today's Mortgage Rate
The monthly payment shown in a mortgage advertisement is not necessarily the payment used to test eligibility. Lenders assess repayment resilience under a higher-rate scenario, which can mean the affordability calculation uses a more demanding payment than the customer's initial quoted instalment.
This is why a mortgage can appear affordable at the offered rate but produce a lower borrowing amount under the lender's stress-tested affordability calculation.
Being Below 50% Is Necessary in Many Cases — but It Is Not the Whole Approval
Being below the 50% ceiling clears only one part of the affordability framework. The lender still has to decide what income it will recognise, how it treats the liabilities, whether the mortgage remains affordable under stress, and whether the borrower's credit, employment or business profile and selected property fit its policy.
Passing the DBR test does not mean you have passed the mortgage application. It means one important constraint may be within range.
DBR Is One Gate in a Wider Mortgage Assessment
DBR
Can your income support total monthly debt repayments?
Income treatment
How much of your salary, commission, business or rental income will the lender recognise?
LTV
How much of the property's accepted value can the bank finance?
Credit & property
Does your overall profile and chosen property fit the lender's risk policy?
Your Deposit and Your DBR Set Different Limits on the Property Budget
A large deposit does not solve an affordability shortfall. You can have enough cash to meet the equity requirement on a property and still be unable to support the mortgage payment the remaining purchase price requires.
Your cash answers “How much can I contribute?” DBR helps answer “How much debt can my income support?” A workable purchase needs both answers to align.
From DBR Headroom to Mortgage Capacity: A Practical Example
Commitment | Monthly amount |
|---|---|
Qualifying income | AED 35,000 |
Car loan | AED 2,800 |
Personal loan | AED 2,200 |
Other recognised credit commitment | AED 1,000 |
Total existing commitments | AED 6,000 |
AED 35,000 × 50% = AED 17,500 AED 17,500 − AED 6,000 = AED 11,500 theoretical additional debt-service capacity before the remaining lender tests.
If DBR Is Too High, Find the Liability Creating the Constraint
If DBR is constraining the mortgage, identify what is consuming the capacity before changing anything. The pressure may come from a personal loan, car finance, an existing mortgage, credit facilities or a combination of commitments rather than from insufficient salary alone.
The next step is diagnosis: determine which recognised liability is limiting affordability, what it would cost to reduce or settle it, and whether doing so improves the mortgage position enough to justify using that cash.
Paying Off the Right Debt Can Improve Mortgage Capacity
Position | Before settlement | After settlement |
|---|---|---|
Income | AED 30,000 | AED 30,000 |
Existing commitments | AED 8,000 | AED 5,000 |
Remaining capacity vs 50% ceiling | AED 7,000 | AED 10,000 |
Mortgage capacity can sometimes improve more efficiently by removing the right monthly commitment than by focusing only on a higher income figure.
But debt settlement is not automatically the best answer. Compare the affordability benefit with settlement costs, the cash being used and the liquidity still required for the deposit, purchase costs and post-completion reserves.
Check DBR Before the Property Creates a Deadline
Risky sequence
Find property → negotiate → commit deposit → apply for mortgage → discover DBR problem.
Better sequence
Review income → review liabilities → estimate DBR → identify suitable lenders → pre-approval → property search.
For Self-Employed Applicants, the Hard Part Is Often the Income Figure
For a self-employed applicant, the DBR formula may be simple while the income input is not. The lender first has to establish what level of business-derived income is sufficiently verifiable and sustainable to use. Company financials, banking, profitability, turnover, ownership, liabilities and trading history can all contribute to that assessment.
Rental Income Only Helps to the Extent the Lender Recognises It
Rental income can support affordability where the lender is prepared to recognise it, but the amount used may differ from the headline annual rent. The lender may require evidence and apply its own treatment rather than simply dividing annual rent by twelve and using the full figure.
Common DBR Assumptions That Can Distort Your Property Budget
Mistake | Why it matters |
|---|---|
Looking only at salary | Existing liabilities can materially reduce capacity |
Ignoring credit facilities | Banks assess overall credit exposure |
Taking a personal loan before applying | The new instalment can reduce mortgage affordability |
Assuming 50% guarantees approval | 50% is a ceiling, not an entitlement |
Using today's rate only | Affordability is stress-tested |
Assuming all income counts at 100% | Variable and non-standard income may be treated differently |
Buying before checking DBR | You can commit to a property outside realistic financing capacity |
DBR and LTV Limit Different Sides of the Same Purchase
DBR asks:
Can your income support the debt repayments?
LTV asks:
How much of the property's accepted value can the bank finance?
You can pass one and fail the other. Mortgage eligibility needs both borrower affordability and property financing limits to work.
Estimate the Headroom Before You Estimate the Mortgage
Use the calculator as a planning tool to see how existing monthly commitments consume income before a proposed mortgage is added. The result is an illustration of DBR headroom — not a lender approval or borrowing quote.
Total existing commitments— Current DBR— Selected monthly debt ceiling— Remaining theoretical capacity— Indicative mortgage from capacity— Headroom to selected ceiling— Planning note— If car loan were removed— If personal loan were removed— If both were removed—
Debt Burden Ratio FAQs
What is the maximum DBR for a UAE mortgage?
The general maximum is 50% of gross salary and qualifying regular income, although lenders still make an individual affordability assessment.
Does the proposed mortgage payment count toward DBR?
Yes. The proposed mortgage forms part of the lender's overall affordability and repayment-burden assessment.
Do personal loans affect mortgage eligibility?
Yes. Their monthly instalments consume part of the income available for total debt servicing.
Does car finance affect DBR?
Yes. Existing vehicle finance can reduce the capacity available for a proposed mortgage.
Do credit cards affect DBR?
They can. Banks consider credit-card and other credit exposure when assessing the borrower's overall financial obligations.
Is a DBR below 50% enough to get a mortgage?
No. The lender still considers stress-tested affordability, credit history, qualifying income, employment or business profile, LTV, property and internal underwriting policy.
Can reducing debt increase my mortgage amount?
Potentially. Reducing a legitimate monthly liability may create more capacity within the DBR calculation, though settlement costs and liquidity should also be considered.
Can a mortgage broker change my DBR?
No. A broker cannot legitimately manipulate DBR. The value is in assessing the profile correctly and identifying lenders whose policies suit the applicant's actual circumstances.