AECB Credit Score and Your UAE Mortgage
Understand how your AECB Credit Score and Credit Report can affect a UAE mortgage, what lenders review, how payment history and credit exposure matter, and why score alone does not determine approval.
Miracle Keys Advisory Team
UAE Mortgage Specialists
Your AECB Score Is a Risk Indicator — Not a Mortgage Decision
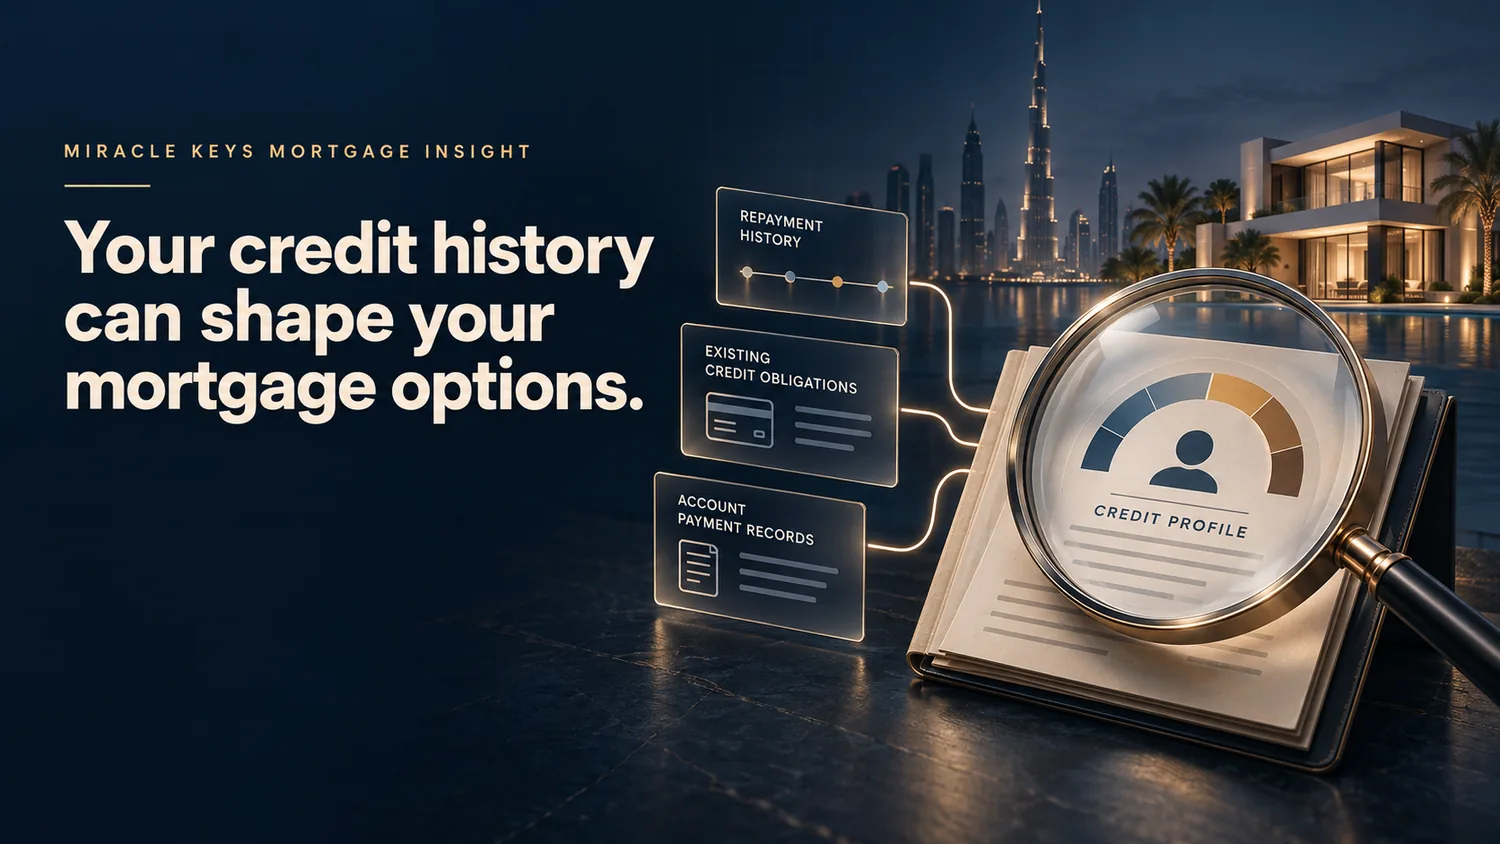
The AECB Credit Score is a three-digit risk indicator ranging from 300 to 900. A higher score generally indicates lower predicted credit risk. For a mortgage applicant, however, it should be read as part of the credit profile — not as a standalone approval or rejection number.
AECB score ≠ mortgage decision. The lender still has to decide whether your income, liabilities, credit behaviour, affordability and the proposed mortgage fit its underwriting criteria.
What Sits Behind the AECB Credit Score
Credit management
How you manage available facilities and credit exposure can influence the profile.
Payment track record
On-time repayment behaviour is an important part of the credit picture.
Credit contracts
The number and type of active credit facilities can matter.
Recent credit activity
New facilities and enquiries can provide additional context to lenders.
Why Lenders Look Beyond Mortgage Affordability
Mortgage underwriting is not only about whether today's monthly payment appears affordable. The lender also wants to understand how existing credit has been managed, what obligations already exist and whether the overall borrowing pattern supports another long-term commitment.
Think of AECB as part of the lender's evidence about how you borrow and repay — not as a box that simply passes or fails the mortgage.
There Is No Universal AECB Mortgage Approval Score
There is no single AECB score that should be presented as a universal UAE mortgage approval threshold. A score that is acceptable within one lender's overall assessment does not create an entitlement to approval elsewhere, and a strong score cannot override other weaknesses in the application.
Do not reduce mortgage eligibility to a target credit-score number. The underwriting decision is broader than the score.
The Score Is the Snapshot; the Credit Report Provides the Context
AECB Credit Score | AECB Credit Report |
|---|---|
Three-digit risk indicator | Detailed credit information |
Range: 300–900 | Shows the underlying credit profile |
Useful snapshot | Provides payment and facility context |
Not a mortgage approval | Supports lender risk assessment |
Repayment History Can Matter More Than a Single Number Suggests
Late-payment history can matter because the lender is assessing future repayment risk from past credit behaviour. The context matters: an isolated historical issue can present differently from recent or repeated arrears, and the lender may consider severity, recency, frequency and whether the position was subsequently regularised.
Credit Cards Can Affect Both Risk and Affordability
Credit cards can affect the mortgage assessment in two different ways: they form part of the credit-behaviour picture and they can also affect affordability. A card showing no current balance should not automatically be assumed irrelevant, because the lender may still consider the available facility and its own methodology for recognising card exposure.
Available Credit Can Still Be Relevant
Facility | Credit limit |
|---|---|
Card 1 | AED 50,000 |
Card 2 | AED 30,000 |
Card 3 | AED 20,000 |
Total available limits | AED 100,000 |
That does not mean applicants should automatically close or reduce every card before applying. First establish how the intended lender treats the facilities; unnecessary changes made without a mortgage strategy can create activity without solving the actual underwriting issue.
Existing Loans Reduce the Capacity Available for a Mortgage
Financial position | Monthly amount |
|---|---|
Qualifying income | AED 30,000 |
Personal loan | AED 4,000 |
Car finance | AED 2,500 |
Other recognised commitment | AED 500 |
Total existing commitments | AED 7,000 |
AECB and DBR Measure Different Parts of the Same Borrowing Picture
AECB and affordability answer related but different questions. Credit information helps the lender understand existing facilities and repayment behaviour; recognised commitments then feed into the lender's affordability and DBR assessment.
A strong score does not create affordability, and strong affordability does not erase adverse credit behaviour. Both sides of the assessment have to work.
A High AECB Score Does Not Override the Rest of the Mortgage
No. A high score can strengthen the credit side of the application, but mortgage approval still depends on recognised income, liabilities, affordability, employment or business profile, age and term, deposit and LTV, the selected property, valuation and lender-specific policy.
A Lower Score Needs Diagnosis, Not an Automatic Rejection
Potentially. The useful starting point is not the score in isolation but the reason behind it. A lower score driven by high exposure can present a different underwriting issue from one associated with recent missed payments or a more complex history. The lender's interpretation of the full report matters.
Do not ask only “Is my score high enough?” Ask “What will the lender see behind the score, and is there anything in that history that needs to be addressed before I apply?”
Improve the Credit Profile, Not Just the Number
Pay obligations on time
Consistent repayment behaviour helps strengthen the overall credit profile.
Manage credit responsibly
Available limits should not be treated as spending targets.
Avoid unnecessary borrowing
New facilities can complicate both credit and affordability.
Review the report
Know what lenders are likely to see before applying.
Credit Improvement Does Not Follow a Guaranteed Timeline
There is no credible universal timetable for improving a credit score. The path depends on what is affecting the profile, whether the reported information is accurate and how subsequent credit behaviour develops. A genuine improvement in the underlying profile matters more than chasing a particular number by a particular date.
If the mortgage depends on the credit profile improving, establish the financing position before committing to a property deadline.
Apply Strategically — Not Everywhere at Once
Submitting applications indiscriminately is not a substitute for understanding the case. Review the credit profile and affordability first, identify the lenders whose criteria fit the borrower, and then submit where there is a reasoned basis for doing so.
If the Report Is Wrong, Correct the Data Before Relying on It
If information in the report appears inaccurate, address the data issue through the appropriate official correction route rather than building multiple mortgage applications around information you believe is wrong. Once corrected, review the updated report before relying on it for underwriting.
Identify the record
Confirm which information appears inaccurate.
Use the official correction process
Submit the required request and supporting information.
Review the updated position
Confirm the data before relying on it for a mortgage application.
Do Not Confuse Credit Risk, Affordability and Property Leverage
Measure | Main question |
|---|---|
AECB | How does your credit history and behaviour look? |
DBR | How much of your qualifying income is committed to debt? |
LTV | How much of the property's accepted value can the bank finance? |
How the Credit Profile Fits Into the Full Mortgage Assessment
Qualifying Income
What income will the lender recognise?
Existing Liabilities
What debts and facilities already exist?
AECB Credit Profile
How has existing credit been managed?
DBR
How much monthly debt-service capacity remains?
Stress-Tested Affordability
Can the mortgage remain affordable under a higher-rate scenario?
LTV & Deposit
Can the property be financed at the required level?
Lender Policy
Which banks actually fit the borrower's complete profile?
AECB & UAE Mortgage FAQs
What is a good AECB score for a UAE mortgage?
AECB scores range from 300 to 900, with higher scores generally indicating lower predicted credit risk. There is no single score that guarantees mortgage approval across every UAE bank.
Does a 700 AECB score guarantee mortgage approval?
No. The lender still assesses income, liabilities, DBR, employment or business profile, LTV, property and its own credit policy.
Can I get a mortgage with a low AECB score?
Potentially, depending on the underlying cause, severity of any credit issues and the lender's underwriting policy.
Do late payments affect AECB?
Payment track record is one of the factors that can influence the overall credit profile.
Can I correct an error in my AECB report?
Yes. AECB provides an official correction process for inaccurate information appearing in a credit report.
Does AECB decide whether my mortgage is approved?
No. AECB provides credit information and a risk score. The mortgage lender makes the credit decision.